A direct debit rejected on a Tuesday morning, and the domino effect begins: incident fees, overdraft interest, then a second failed payment triggered by another direct debit. Day-to-day banking isn’t about major wealth-management decisions; it’s about these small events that quietly eat into your budget. Understanding how your account works, what you’re actually charged, and which tools are available can help you avoid most of these unpleasant surprises.
Banking incident fees: what can add up on your statement
We often think of overdrafts as the main source of bank fees. In reality, several types of fees can add up from a single incident. A rejected direct debit can result in an intervention fee, a specific rejection fee, and overdraft interest if your balance goes below zero.
The legal cap on intervention fees doesn’t cover other charges. Your bank’s fee schedule, available at a branch or in your online banking area, lists each one. Reviewing it once a year can help you avoid surprises: fees change, and a rejected direct debit at a traditional bank won’t necessarily cost the same as one at an online bank.
Customers identified as financially vulnerable are eligible for higher caps on incident fees. These specific offers are available across all banking networks, but they aren’t always offered automatically. You may need to ask your adviser directly.
If you’re looking to compare offers and understand differences in fees between providers, Invistita’s banking section features detailed analyses on the subject.
Free instant transfers: a useful tool for managing your money
Since January 2025, an EU regulation has required that instant transfers cost no more than standard transfers. In practice, if online transfers are free with your bank, instant transfers are too. This makes a real difference to day-to-day cash-flow management.
You can now transfer money between your own accounts at different banks in seconds, free of charge. This is especially useful for topping up a current account just before a scheduled direct debit, without waiting the usual one or two business days.
The trade-off: instant transfers can’t be cancelled
Once an instant transfer has been made, it can’t be recalled. Unlike a standard transfer, which can sometimes be cancelled before it’s processed, an instant transfer is final as soon as you confirm it.
Since October 2025, banks have been required to offer a check that the beneficiary’s name matches the IBAN before processing a transfer. This helps reduce the risk of fraud involving fake bank details. Before confirming a transfer to a new beneficiary, always check that the name displayed matches the person or company you intend to pay.
Budget-tracking methods: choose one you can stick with
There’s no shortage of budgeting methods. The real deciding factor isn’t how sophisticated they are, but whether they fit into your routine over the long term.
- The envelope method, using physical or virtual envelopes, involves setting aside a fixed amount each month for each spending category: groceries, transport, leisure. Once an envelope is empty, you stop spending in that category. It works well for people who find it hard to keep track of how much they have left halfway through the month.
- Weekly tracking, using your bank’s app or a simple spreadsheet, means checking each week how your actual spending compares with your budget. A ten-minute check-in every Sunday evening is enough to spot overspending before it leads to an overdraft.
- The proportional budgeting rule—allocating one portion to fixed bills, one to everyday spending, and one to savings—works well for people with a regular income. It’s less effective when income fluctuates from month to month, because fixed proportions don’t adjust to leaner months.
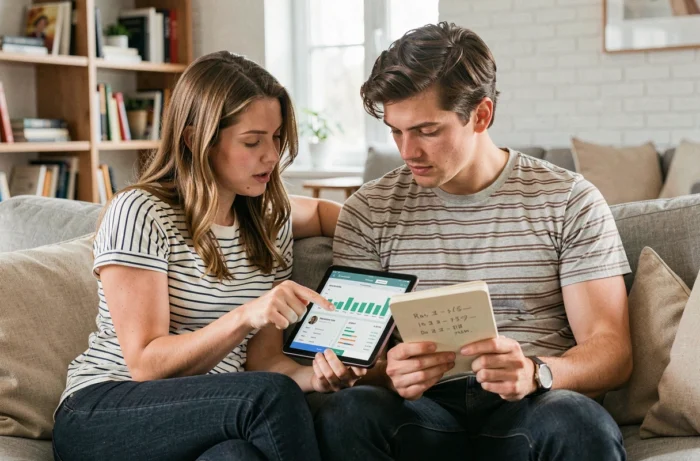
None of these methods will work if you don’t know your actual fixed expenses. Before choosing a system, list all the active direct debits on your account. You’ll often find forgotten subscriptions—sometimes two or three—that add up to a significant amount.
Tools built into banking apps
Most banking apps now automatically categorise spending. Algorithms sort each transaction into categories such as groceries, healthcare, and transport, then display monthly charts. These tools can help you understand how your spending is really distributed, but they’re no substitute for actively managing your budget.
Some banks also offer customisable alerts, such as a notification when your balance falls below a certain threshold or an alert for unusual spending. Turning these on shifts you from passive tracking to proactive management. You can correct an overspend as it happens, rather than facing it at the end of the month on your statement.
Bank overdrafts: a cost that’s often underestimated
An authorised overdraft can feel like a safety net. Its actual cost depends on the overdraft interest rate (which varies by bank), how long you use it, and the amount borrowed. Overdrafts are a common expense, but one that rarely makes it into the budget.
The most effective approach is to treat an authorised overdraft as credit, not as an extension of your balance. Every day your account is overdrawn generates interest. Cutting a few days off your overdraft each month—for example, by moving the date of a non-essential direct debit—automatically reduces the cost.
Asking your adviser to adjust your authorised overdraft limit is another practical option. A limit set too high can encourage you to rely on it more. Bringing it down to what you actually need—that is, enough to cover a temporary cash-flow gap—encourages you to plan ahead instead of reacting after the fact.
Ultimately, day-to-day banking comes down to three things: knowing exactly what your bank charges, making use of the free tools already available in your online banking area, and choosing a tracking method that’s simple enough to keep up every week. The best budget is the one you check regularly, not the one you leave forgotten in a spreadsheet after January.